
Resources
Welcome to our knowledge base of research that demonstrates our understanding of complex business challenges faced by companies around the world.
Featured highlights
Introduction
As data rapidly transforms from an organizational asset into state sovereignty, regional governments are pivoting away from outsourcing their safety to distant, centralized frameworks. Sarawak made a decisive move in late 2026 by launching the Sarawak Cybersecurity Strategy and Roadmap (SCSR) 2030, a comprehensive state-level cybersecurity framework, catering for this very objective. Driven directly by the Sarawak Multimedia Authority (SMA), this 5-year roadmap positions Sarawak as the first state in Malaysia to pioneer its own comprehensive, localized defense infrastructure.
With an ambitious objective to digitalize 100% of its public services by 2030, Sarawak is not just implementing new software, it is building a digital shield. The framework unifies 18 strategic initiatives under 5 core pillars, designed to anchor its massive pushes into green energy, advanced semiconductors, and multi-megawatt data center hubs.
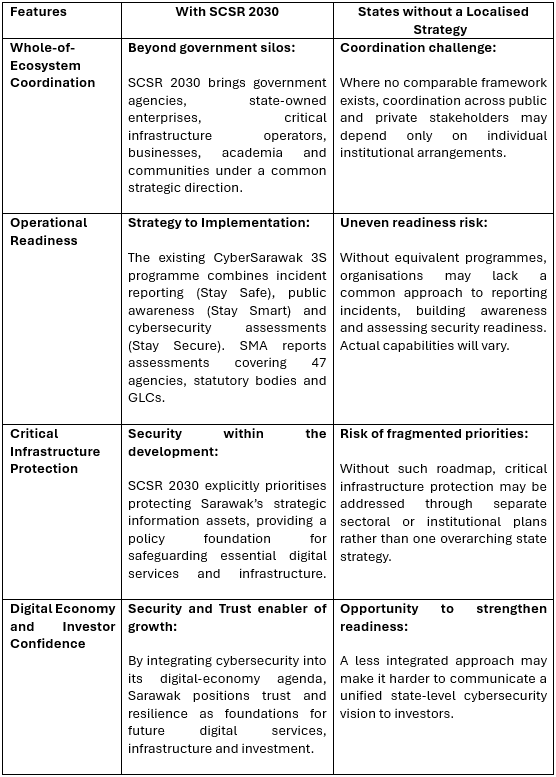
To appreciate the gravity of the SCSR 2030, we examine the features below in isolation:
Cost of Inaction: Real-World Cyber Threats
Cybersecurity vulnerabilities has proven that they bring direct, painful real-world costs, from the exposure of sensitive personal data to disruptions affecting critical infrastructure and substantial financial losses. Recent incidents across East and West Malaysia illustrate the costs from different dimensions of cyber-risk:
1. Swinburne University of Technology Sarawak — Ransomware and data theft
In August 2024,Swinburne University of Technology Sarawak was listed on the dark-web leak site of the RansomHub ransomware group, which claimed to have stolen 366 GB of data. The university subsequently confirmed that investigations had identified the theft of certain sensitive information, including passport scans, student completion letters and student applications, highlighting the risks cyberattacks pose to personal data and institutional trust.
2. Malaysia Airports Holdings Berhad — Cyberattack affecting KLIA systems
On 23 March 2025, a cyber incident affected certain computer systems at Kuala Lumpur International Airport (KLIA), operated by Malaysia Airports Holdings Berhad (MAHB). The incident prompted a full-scale investigation, with MAHB notifying the NACSA and the Civil Aviation Authority of Malaysia. The Prime Minister subsequently disclosed that hackers had demanded a USD10 million ransom, underscoring the potential stakes when cyber threats target critical transportation infrastructure.
3. Sarawak — Rising cybercrime and financial losses
Between 2024 and April 2026, Sarawak recorded 5,875 cybercrime cases involving approximately RM233.48 million in financial losses. Investment scams accounted for approximately RM132.9 million, representing around 57% of the total losses. Kuching recorded RM45.77 million in losses across 782 cases, followed by Miri with RM33.13 million across 766 cases and Sibu with RM20.40 million across 721 cases. These figures demonstrate that cybercrime is not merely a threat to institutions and infrastructure; it also inflicts substantial financial harm on individuals and communities.
4. Malaysia's ransomware threat landscape — Akira and Ransom Hub
A ransomware threat assessment published by Simply Data on 23 August 2026 identified Akira and RansomHub among the ransomware groups associated with attacks on Malaysian organisations during the first half of 2026. The report identified exposed remote-access infrastructure, including VPN appliances and Remote Desktop Protocol (RDP) endpoints, as attack vectors associated with Akira, and linked RansomHub to targets in Malaysia's financial sector. These findings reinforce the need for proactive security controls, effective threat detection and coordinated incident-response capabilities.
Taken together, these incidents illustrate the consequences of cybersecurity being an afterthought. The damage extends beyond technical disruption to personal data breaches, financial losses, threats to essential services and a loss of public trust. For businesses at the digital forefront, this presents another challenge. Innovation comes with a cost of compliance that must be factored into the business from the outset, rather than addressed only when regulatory requirements arise or an incident occurs.
In this context, the SCSR 2030 strategy prompts an important question: does introducing state-level oversight alongside existing federal regulations create an overregulated environment? Not necessarily. Instead, state-level initiatives should serve as a wake-up call for companies to view security as a core component of responsible innovation. The true test will be ensuring that state and federal frameworks align seamlessly, offering clear, balanced requirements rather than redundant paperwork that fails to improve actual protection.
We can see clearly how the SCSR 2030 has established a critical precedent. SCSR 2030 offers a framework for making cybersecurity an integral part of digital development, rather than an afterthought. The SCSR 2030 further ensures that as the state scales its digital ambitions, from localised AI hubs to smart utility grids, its sovereignty remains uncompromised. For the rest of the country, this precedent is an important one, the future lies in resilience, and it belongs to those who retain the power to protect, govern and control what they build.
This article was authored by Jonathan Lim, Managing Partner, and Laurel Lim, Senior Associate, with contributions from Nadarashnaraj Sargunaraj, Partner, and Mohamad Izahar Mohamad Izham, Partner.
This article is for general informational purposes only and does not constitute legal advice. Please contact us if you require advice on how these developments may affect your business.
The Digital Shield: Sarawak’s Building Blocks for a Fortress for its Digital Economy
One of the original promises of digital assets was simple: value moving across borders with minimal friction and full transparency. Today, Malaysia is taking steps towards that vision, developing regulated digital asset infrastructure intended to support domestic financial innovation and potentially enhance regional market integration.
Through Bank Negara Malaysia’s (BNM) Digital Asset Innovation Hub (DAIH), launched in June 2025, Malaysia has established a dedicated environment to test real-world applications. The DAIH currently emphasises testing tokenised bank deposits, while BNM’s broader strategic horizon continues to explore tokenised sukuk, stablecoins and automated supply chain finance. If this roadmap is anchored in institutional liquidity and cross-border commercial trade, Malaysia has the potential to reduce structural friction and unlock real economic value within a live banking ecosystem. The Securities Commission Malaysia (SC) is also relevant to the digital asset and tokenised capital markets framework, including tokenised sukuk. The boundary between the BNM and SC perimeters is itself an interoperability question: participants need clarity on which regulator governs each asset, activity and point in the transaction chain.
Across Asia, neighbouring jurisdictions are advancing their own tailored regulatory regimes. Singapore, for instance, has been moving beyond initial proofs of concept under Project Guardian and developing commercial digital infrastructure through Global Layer One (GL1) and settlement networks such as BLOOM, while its framework for digital payment tokens (DPTs) under the statutory Payment Services Act (PSA) and its regulatory framework for single-currency stablecoins continue to evolve. Hong Kong’s stablecoin licensing regime, which came into effect in August 2025, offers a useful comparator for how reserve-backed digital money may be supervised. Meanwhile, Taiwan has enacted a statutory framework specifically for virtual asset service providers (VASPs), although its Virtual Asset Service Act has not yet entered into force.
Individually, these domestic frameworks represent major regulatory milestones. But what happens between them when a transaction crosses a border?
Consider a scenario where a ringgit stablecoin or tokenised deposit issued under BNM’s DAIH framework interacts with an institution operating under Singapore’s PSA regime, or where a tokenised asset residing in Malaysia is settled using digital fiat originating from a foreign market. While ledger transfers execute in seconds, the underlying legal, regulatory, and institutional mechanics remain firmly bound to national borders. Critical friction points immediately surface:
- Regulatory Perimeter & Licensing: Which jurisdiction holds primary licensing authority when digital asset services, custody nodes, and smart contract execution layers span multiple borders?
- Monetary & Sanctions Reconciliation: How are foreign exchange controls, capital flow management measures, and disparate AML/CFT or sanctions screening standards reconciled between distinct payment regimes?
- Private Law & Insolvency Finality: In cross-border collateral transfers or tokenised asset defaults, which country's legal system determines property rights, choice-of-law priority and custody ring-fencing during an insolvency event? For example, if a tokenised asset held for a Malaysian investor is custodied in Singapore and the Singapore custodian becomes insolvent, does Malaysian law, Singapore law or the governing law of the tokenised asset determine whether the asset is ring-fenced from the custodian’s creditors? The answer may depend on the asset, the custody structure and the applicable conflict-of-laws rules.
Beyond Sandboxes: Building Interoperable Architecture
Sandboxes like BNM’s DAIH are essential for evaluating technical viability and informing national policy. However, a sandbox or regulatory perimeter in one market cannot, by itself, determine how a Malaysian digital asset structure legally interacts with counterparties in Singapore, Hong Kong, or beyond. That requires an overlay of legal and regulatory interoperability operating across borders.
Multilateral central bank initiatives, such as Project Mandala, led by the BIS Innovation Hub with participating central banks including BNM, MAS, Reserve Bank of Australia, Banque de France, Reserve Bank of India, Central Bank of Kuwait, Bangko Sentral ng Pilipinas takes a major step forward by exploring how regulatory parameters can be embedded directly into transaction protocols. Yet, protocol-level "compliance-by-design" is only one layer of the solution.
The surrounding legal architecture, from institutional custody agreements and master clearing documentation to the cross-border enforce ability of smart contracts must be equally interconnected. For institutional market participants, cross-border interoperability is no longer a theoretical debate. Regulatory posture is increasingly transitioning from a domestic compliance checkbox to a core pillar of regional commercial strategy.
Bridging the Gap: What Interoperability Requires
Technical interoperability is necessary but insufficient. Cross-border digital asset markets also require a legal and regulatory framework that can travel with the transaction.
- Mutual recognition or passporting between regulators, supported by clear limits and supervisory cooperation;
- Harmonised conflict-of-laws approaches, drawing where appropriate on the UNIDROIT Principles on Digital Assets and Private Law;
- Alignment of the FATF Travel Rule across corridors to support consistent AML/CFT controls;
- Standardised cross-border documentation, including master agreements and custody terms;
- ASEAN-level coordination to reduce fragmentation while preserving appropriate national safeguards.
The answer to the question posed above is yes—but only if legal interoperability is built alongside technical interoperability.
What This Means for Market Participants
For market participants, the practical agenda is immediate:
- Map the licensing touchpoints of each cross-border flow, including issuance, custody, settlement and technology services;
- Stress-test governing-law and insolvency provisions in tokenisation documentation, including the treatment of assets held through an overseas custodian;
- Align AML and sanctions screening across relevant corridors, with clear responsibility for Travel Rule information;
- Engage early with DAIH and relevant regional initiatives to test legal, regulatory and technical assumptions before scaling.
The Road Ahead
The next phase of digital assets in Asia will not merely be about perfecting domestic frameworks within individual borders; it will be about making those frameworks work together in practice. Market participants should treat legal interoperability as a design requirement: identify licensing perimeters, document governing-law and insolvency outcomes, and align AML/CFT controls before a transaction crosses a border.
Malaysia’s DAIH and regional initiatives could provide practical forums to test that approach. The jurisdictions that connect regulatory, legal and technical layers will be best placed to turn tokenisation into durable cross-border infrastructure.
This article is written by Managing Partner, Jonathan Lim and Senior Associate, Laurel Lim.
This article is for general informational purposes only and does not constitute legal advice. Please contact us if you require advice on how these developments may affect your business.
Asia Can Regulate Digital Assets, But Can It Connect Them?
1. Introduction
One of the most common misconceptions in capital markets is that a ṣukūk is simply the Islamic equivalent of a conventional bond. Both instruments can achieve a similar funding outcome for issuers, and both provide investment returns to investors. Yet this surface-level resemblance conceals a fundamental divergence in their legal and structural foundations. A conventional bond is generally a debt obligation: the investor lends money to the issuer and, in return, receives periodic interest payments and the repayment of principal over the life of the instrument. A ṣukūk, by contrast, is typically structured around ownership or beneficial interests in assets, usufructs, investments, or business ventures. Rather than representing a pure debt claim, ṣukūk structures are designed to comply with Sharīʻah principles by linking investors to an underlying asset or economic activity.
This distinction is not merely theoretical. It carries profound implications for how ṣukūk ought to be classified, regulated, taxed, and treated in the capital adequacy frameworks of financial institutions. If a ṣukūk genuinely embeds risk-sharing, links returns to the performance of real assets, and avoids guaranteeing the return of capital, then it may more accurately be characterised as an equity investment rather than a debt obligation.
Can ṣukūk be properly treated as equity investments? Drawing on the AAOIFI’s evolving standards, the proposed exposure draft SS ED 62, the International Accounting Standard 32 (“IAS 32”) classification framework, and recent proposals for mushārakah-based infrastructure ṣukūk in Malaysia, it does appear that certain ṣukūk structures—particularly those built on muḍārabah and mushārakah contracts—can and should be recognised as equity or quasi-equity instruments. The barriers to this recognition are institutional and behavioural, not technical or Sharīʻah-based.
2. The Debt–Equity Spectrum: Where Do Ṣukūk Sit?
Conventional financial taxonomy operates along a binary axis: instruments are either debt or equity. Bonds, loans, and notes sit firmly on the debt side; ordinary shares and partnership interests sit on the equity side. Ṣukūk, however, do not fit neatly into either category. They are, by design, hybrid instruments whose characteristics straddle the debt–equity divide.
A muḍārabah ṣukūk, for example, involves one party providing capital and another providing entrepreneurial expertise. The investor’s return is a share of the profits generated by the venture, not a fixed coupon. If the venture generates no profit, the investor earns nothing. If the venture incurs losses, the investor bears those losses to the extent of the capital contributed. This structure carries unmistakable equity-like features: residual, participatory claims on performance rather than a fixed, unconditional right to repayment.
A mushārakah ṣukūk takes this further. Here, multiple parties contribute capital to a joint venture and share both profits and losses in agreed proportions. The certificate holders become co-owners of the underlying venture or assets. Their returns are linked directly to the venture’s performance, and their exposure extends beyond the creditworthiness of any single originator.
Yet both muḍārabah and mushārakah ṣukūk also carry features associated with debt instruments. They typically have a defined maturity date, a terminal redemption mechanism, and—in practice—structures that provide investors with a degree of capital protection through purchase undertakings or liquidity facilities. The hybrid character of these instruments, combining features of both debt and equity, makes them susceptible to the agency problems associated with both financing forms simultaneously.
Some scholars have suggested that this taxonomic ambiguity could be resolved by adopting an alternative designation. The term “Islamic Investment Certificates” (IICs) has been proposed to signal that the instruments are fundamentally equity-like and risk-sharing in nature, rather than fixed-income obligations dressed in Islamic nomenclature.
It is important to note the regulatory context. Under Malaysian law, a ṣukūk is generally included within the statutory definition of a “debenture.” This means that, for certain legal and regulatory purposes, ṣukūk and conventional debt securities may be treated similarly. However, as the Securities Commission Malaysia has itself acknowledged, this regulatory treatment does not make a ṣukūk a conventional bond. The inclusion is a matter of administrative convenience and investor protection, not a determination of economic substance.
3. The Case for Equity Treatment
The strongest case for treating ṣukūk as equity investments arises from structures built on mushārakah (joint venture) contracts, particularly where the ṣukūk are deployed in infrastructure projects.
Academic proposals for Mushārakah-based sovereign sukuk structures suggest that equity characteristics can be embedded through the instrument's risk-sharing architecture and governance design, rather than through nomenclature alone.
3.1 Genuine Co-ownership, Not a Debt Claim
The proposed mushārakah structure establishes genuine co-ownership in infrastructure assets rather than a debt claim against the originator. Certificate holders acquire undivided proportional ownership interests in the underlying project assets—toll roads, power plants, water treatment facilities—and their returns flow from the economic performance of those assets. This is fundamentally different from a conventional bond, where the investor's claim is against the issuer's general creditworthiness.
The AAOIFI's proposed exposure draft, SS ED 62, reinforces this distinction. Clause 2/1 defines ṣukūk as:
Equal-value investment securities representing undivided common ownership interests in underlying assets, whether tangible assets, usufructs, rights, debts, cash, or any combination thereof, that give rise to rights and obligations for certificate holders arising from their proportional ownership share.
This definition places ownership—not lending—at the centre of the ṣukūk relationship.
3.2 Five Distinguishing Characteristics
SS ED 62 Clause 3 enumerates five characteristics that distinguish ṣukūk from conventional bonds:
- Not based on interest-bearing lending (Clause 3/1). Ṣukūk returns derive from asset ownership or venture participation, not from the time value of money lent.
- Principal and profit are not automatically obligations of the originator (Clause 3/2).Unlike a bondholder, a ṣukūk certificate holder does not have an unconditional right to demand repayment of capital or a guaranteed return.
- Certificate holders share both the rewards (ghunm) and the burdens (ghurm) (Clause 3/3).The Sharīʻah maxim of al-ghunm bi al-ghurm mandates that entitlement to profit must be accompanied by exposure to loss.
- Issued pursuant to Sharīʻah contracts (Clause 3/4). The governing contracts determine the nature and extent of the certificate holder’s rights, which may differ materially from conventional fixed-income instruments.
- Risks are not confined to the originator's credit risk (Clause 3/5). Certificate holders are exposed to the performance risk of the underlying assets or venture, not merely to whether the originator can service its debts.
3.3 Elimination of Fixed Financial Obligations
A defining feature of the proposed mushārakah structure is the elimination of fixed financial obligations. There are no fixed profit payments. There is no guaranteed return of principal. Returns are linked entirely to the actual performance of the underlying infrastructure project.
SS ED 62 Clause 11/2/3 prohibits separating the profits of the ṣukūk from the returns of its underlying assets, reinforcing the requirement that ṣukūk returns must be genuine and performance-linked rather than predetermined.
The structure further provides that any purchase undertaking must be at fair market value determined at the time of the transaction, and must not be mandatory. This avoids the capital guarantee mechanisms that have historically rendered many ṣukūk debt-like in substance. The government's in-kind contribution—land, concession rights, or existing infrastructure—constitutes a capital contribution to the mushārakah venture rather than collateral securing a debt obligation.
3.4 Quasi-Equity Recognition
The AAOIFI has recognised the quasi-equity nature of these instruments in its accounting standards. Both muḍārabah and mushārakah ṣukūk should be understood as quasi-equity instruments: their returns are linked to the performance of real underlying assets rather than to a contractual obligation to pay a fixed amount. They do not fall within the category of fixed-income securities.
AAOIFI has introduced a quasi-equity classification in financial reporting, acknowledging that these instruments integrate characteristics of both debt and equity. This classification is significant because it provides a formal accounting framework that recognises the hybrid nature of risk-sharing ṣukūk without forcing them into the binary debt-or-equity taxonomy of conventional finance.
4. The IAS 32 and Accounting Perspective
The accounting classification of a financial instrument as equity or liability is governed by IAS 32, Financial Instruments: Presentation. Critically, IAS 32 requires classification based on the economic substance of the contractual arrangement, not its legal form. The label attached to an instrument—whether “ṣukūk,” “bond,” “note,” or “certificate”—is irrelevant to its accounting treatment. What matters is the nature of the rights and obligations created by the contract.
The key test under IAS 32 is whether the issuer has a contractual obligation to deliver cash or another financial asset to the holder. If such an obligation exists, the instrument is classified as a financial liability. If it does not, the instrument may be classified as equity.
In the context of the proposed mushārakah-based ṣukūk, three features are determinative:
- No fixed repayment obligation. The government does not contractually undertake to return the investors' capital at a fixed amount. Redemption, if it occurs, is at fair market value.
- No fixed return obligation. Returns to certificate holders are a share of the project's actual performance, not a predetermined coupon.
- Non-binding purchase undertaking. Provided the purchase undertaking is drafted as a non-binding option rather than a binding obligation, the issuer is not contractually compelled to repurchase the ṣukūk at maturity.
If these conditions hold, the instrument may be classified as equity or as a hybrid instrument without a liability component under IAS 32. The IFRS classification decision tree confirms this analysis: where there is no contractual obligation to deliver cash, the instrument falls on the equity side of the classification.
The government's in-kind contribution—land, concession rights, or existing infrastructure asets—should be recognised as an equity investment inthe mushārakah venture rather than as a debt obligation. This treatment reflects the economic reality of the arrangement: the government is contributing capital to a joint enterprise, not borrowing money that must be repaid.
Classification as equity rather than debt directly affects the government's balance sheet, its debt-to-GDP ratios, its fiscal headroom, and the capital adequacy treatment of institutions holding the ṣukūk. If the instrument is properly classified as equity, it does not increase the sovereign debt burden—a significant advantage for governments seeking to finance infrastructure without expanding their liabilities.
5. Regulatory and Capital Adequacy Challenges
Despite the strong Sharīʻah and accounting arguments for equity treatment, regulatory frameworks remain stubbornly debt-centric. In Malaysia, once an instrument is labelled a “ṣukūk,” it is often automatically treated as debt or fixed income, regardless of the nature of the underlying contract. This regulatory presumption creates a self-reinforcing cycle: issuers structure ṣukūk to behave like debt because regulators classify them as debt, and regulators classify them as debt because issuers structure them to behave that way.
Capital adequacy requirements compound the problem. Under the standards issued by the Islamic Financial Services Board (IFSB), capital requirements of 300 to 400 per cent are imposed on mushārakah exposures under certain approaches. These charges are disproportionately high relative to the actual risk profile of well-structured, revenue-generating infrastructure partnerships. The result is that financial institutions face a punitive capital cost for holding risk-sharing ṣukūk, which in turn depresses demand and discourages issuance.
Bank Negara Malaysia (BNM) assigns a credit risk weight of approximately 150 per cent to certain mushārakah and muḍārabah exposures. However, BNM’s Capital Adequacy Framework for Islamic Banks (CAFIB) also provides for a supervisory slotting approach, under which the risk weight is determined by the quality of the underlying exposure rather than its contractual label. A well-structured, revenue-generating sovereign infrastructure partnership could credibly attain a “strong” or “good” slotting classification, attracting a risk weight of 70 to 90 per cent—significantly lower than the standard mushārakah charge.
Importantly, BNM’s CAFIB requires the regulatory capital treatment of any ṣukūk to follow its economic substance and actual risk profile rather than its legal form. This is a critical principle. It means that, in theory, a mushārakah ṣukūk structured with genuine risk-sharing and backed by revenue-generating infrastructure assets need not attract the punitive capital charges that deter banks from holding such instruments.
The regulatory challenge, then, is not one of principle but of practice. The principle of substance over form is well-established in both accounting and prudential regulation. The difficulty lies in translating that principle into consistent regulatory practice, particularly when the default taxonomy treats all ṣukūk as debt. As the IERIF report observes, regulatory classification as “debt” is a matter of regulatory taxonomy rather than economic substance. From both Sharīʻah and accounting perspectives, what is determinative is the underlying structure and allocation of risk, not the terminology applied by regulators.
6. Market Resistance and Behavioural Barriers
Even where the legal, Sharīʻah, and accounting arguments for equity treatment are compelling, market practice has consistently resisted the shift. The barriers are deeply embedded in the institutional culture of Islamic capital markets.
The entrenched mindset that equates ṣukūk with debt is perhaps the most formidable obstacle. For decades, market participants—issuers, arrangers, investors, rating agencies, and regulators—have operated on the assumption that ṣukūk are the Islamic equivalent of bonds. Pricing conventions reflect this: ṣukūk are typically priced off a benchmark yield curve, with a fixed or floating "profit rate" that mirrors a conventional coupon. Purchase undertakings at fixed redemption amounts are commonplace, providing investors with effective capital protection that renders the instruments debt-like in economic substance, whatever their Sharīʻah characterisation.
Investor preferences have been shaped by decades of experience with capital-guaranteed products. Institutional investors—pension funds, insurance companies, sovereign wealth funds—are mandated or accustomed to investing in instruments that provide predictable cash flows and capital preservation. A genuinely risk-sharing ṣukūk, where returns fluctuate with project performance and capital is at risk, does not fit comfortably within these investment parameters.
Historical episodes have reinforced these behavioural patterns.
A frequently cited example is the pre-2008 generation of Mushārakah sukuk, many of which incorporated purchase undertakings requiring the originator or managing partner to repurchase the sukuk assets at face value upon maturity or dissolution. Although labelled as Mushārakah and therefore ostensibly equity-based, the fixed-price repurchase mechanism effectively guaranteed investors' capital and substantially reduced their exposure to partnership losses, leading scholars and the AAOIFI Shari'ah Board to criticise such structures as debt-like in economic substance
A notable example is the US$1 billion 2007 sukuk issued by Dana Gas PJSC, which utilised a Mudarabah structure accompanied by a purchase undertaking requiring the obligor to acquire the sukuk holders' interest upon dissolution for a predetermined exercise price. Although the instrument was structured as a profit-sharing investment, the purchase undertaking substantially mitigated investors' exposure to capital loss and rendered the transaction economically closer to a debt instrument than a true risk-sharing venture. The structure exemplifies how the legal and economic substance of a sukuk may diverge from its formal characterisation as an equity-based instrument. The Dana Gas ṣukūk required a Sharīʻah ruling acknowledging non-compliance after payment difficulties emerged, highlighting the tension between stated Sharīʻah structures and actual market practice.
These examples illustrate a persistent pattern: ecosystem pressures consistently push issuers, arrangers, and rating agencies towards fixed-income conventions even where contracts are nominally structured as profit-sharing. The result is a market in which the form of Islamic finance is maintained—mushārakah contracts are used, assets are identified, Sharīʻah boards provide approvals—but the substance remains indistinguishable from conventional debt.
Rating agencies contribute to this dynamic. Their methodologies are calibrated for fixed-income instruments, assessing the issuer's ability to make scheduled payments and repay principal. A genuinely equity-like ṣukūk, where the certificate holder’s return depends on project performance rather than the issuer's credit strength, does not map well onto existing rating frameworks. Without a credit rating, many institutional investors cannot or will not invest, regardless of the instrument's underlying quality.
7. The Path Forward
If ṣukūk are to fulfil their potential as genuine equity or quasi-equity instruments—and if the Islamic capital markets are to move beyond the replication of conventional debt—a coordinated programme of policy and market reform is required. This could include:
- A formal national framework recognising risk-sharing ṣukūk as non-debt financing. An explicit regulatory classification that distinguishes risk-sharing ṣukūk (built on mushārakah and muḍārabah) from asset-backed or debt-replicating structures could be introduced. This framework could recognise that instruments with genuine risk-sharing, no capital guarantees, and performance-linked returns are equity or quasi-equity instruments, not debt obligations.
- Pilot implementation with brownfield infrastructure projects. Initial deployment should prioritise brownfield and upgrade-type projects—existing toll roads, power plants, or utilities with established revenue histories. These projects offer observable cash flow track records, reducing the information asymmetry that deters equity investors and enabling more confident valuation.
- Recalibration of capital adequacy charges. Regulators should ensure that the supervisory slotting approach is applied consistently to well-structured mushārakah ṣukūk, so that capital charges reflect the actual risk profile of the instrument rather than the punitive default weights for equity exposures. A sovereign infrastructure mushārakah with stable revenue streams should not attract the same capital charge as a speculative equity position.
- Tax neutrality between debt and risk-sharing instruments. Tax asymmetries that favour debt—such as the deductibility of interest payments but not profit-sharing distributions—must be corrected. Without tax neutrality, issuers will continue to prefer debt-like structures for purely fiscal reasons, regardless of Sharīʻah considerations.
- Introduction of an "Islamic Investment Certificates" classification. The adoption of a new classification, such as Islamic Investment Certificates, would signal to the market that these instruments are fundamentally different from conventional bonds. Nomenclature matters: as long as ṣukūk are labelled and categorised alongside bonds, the market will treat them as bonds.
- Phased implementation roadmap. Reform should proceed incrementally. A pilot programme with a limited number of well-structured issuances, supported by regulatory guidance and investor education, would build the evidence base and market confidence needed for broader adoption.
These reforms are not utopian. Each builds on principles already embedded in law, AAOIFI standards, and international accounting frameworks. What is required is the institutional will to apply those principles consistently and to resist the gravitational pull of debt-centric conventions.
8. Conclusion
A ṣukūk built on a mushārakah or muḍārabah contract, with genuine risk-sharing between issuer and investors, no capital or return guarantees, returns linked to the performance of real underlying assets, and natural exit mechanisms at fair market value, possesses the essential characteristics of an equity or quasi-equity instrument. The AAOIFI's proposed SS ED 62 standards confirm this. The IAS 32 classification framework supports it. The Sharīʻah principles of al-ghunm bi al-ghurm (reward accompanies risk) and the prohibition of ribā demand it.
The barriers to equity treatment are not technical. The legal structures exist. The accounting frameworks accommodate them. The Sharīʻah scholarship supports them. The barriers are institutional and behavioural: entrenched market conventions, debt-centric regulatory taxonomies, misaligned capital charges, tax asymmetries, and investor preferences shaped by decades of capital-guaranteed products.
Malaysia, as the world's largest ṣukūk market and a leader in Islamic finance innovation, is well-positioned to lead this transition. By introducing a formal framework for risk-sharing ṣukūk classification, piloting mushārakah-based structures in brownfield infrastructure projects, recalibrating capital adequacy requirements, and restoring tax neutrality, Malaysia can demonstrate that ṣukūk are not merely bonds with an Arabic name—they are a distinct class of investment instrument, capable of delivering the risk-sharing, asset-backed, real-economy financing that Islamic finance has always promised.
The shift from debt replication to genuine equity participation will not happen overnight. But every regulatory reform, every successful issuance, and every investor who accepts performance-linked returns over guaranteed coupons moves the market closer to what ṣukūk were always intended to be: instruments of shared enterprise, shared risk, and shared reward.
This article is for general informational purposes only and does not constitute legal advice. Please contact us if you require advice on how these developments may affect your business.
Can Sukuk Be Treated As An Equity Investment Rather Than A Debt Obligation?
This is a significant Court of Appeal decision — SA Puncak Management Sdn Bhd v KL Petrogas Sdn Bhd (25 August 2026) — that raises several important and, in some respects, provocative points for Islamic finance in Malaysia. Below is my analysis of the key issues from an Islamic finance perspective.
The Core Holding on the Moneylenders Act
The Court of Appeal reversed the High Court on all four questions, holding that the Islamic Pre-Factoring Facility did not breach s 5(1) of the Moneylenders Act 1951 (MA). The Court drew a critical distinction: s 5(1) MA prohibits the business of moneylending, not a mere activity of moneylending, and criticised the High Court for conflating the two. This was grounded in Federal Court authority from Ngui Mui Khin v Gillespie Bros and Yeep Mooi v Chu Chin Chua, both of which held that the MA targets moneylenders as a class of business, not isolated lending transactions.
The Court further held that whole turnover agreements (receivables purchase agreements) are a recognised form of debt financing, not moneylending, relying on the New Zealand authority of Commercial Factors Ltd v Maxwell Printing Ltd. It also held that even if the MA were engaged, SAPM was exempt under the Exemption Order (P.U.(B) 219/2005), a point the High Court had erroneously restricted to "legitimate factoring" only.
The Treatment of Shariah Non-Compliance — A Critical Point
The most consequential aspect of this judgment for Islamic finance practitioners is the Court of Appeal's treatment of the Shariah compliance question in Section F of the judgment. The Court declined to consider KLP's allegation of exorbitant profit and potential breach of Shariah principles for three reasons:
- Pleading deficiency — KLP's Amended Statement of Claim did not plead that the Islamic Pre-Factoring Facility had breached Shariah principles.
- Scope of the questions — The four questions before the Court did not concern the exorbitant profit allegation, much less a breach of Shariah principles.
- Substantive position — Even if there were a breach of Shariah principles, such a breach in itself does not invalidate the Islamic Pre-Factoring Facility.
On the third point, the Court relied heavily on the Court of Appeal's earlier decisions in Tan Sri Halim bin Saad v Amanah International Finance Bhd [2026] 2MLJ 570, and within that, the judgment of Rohana Yusuf JCA in Maybank Islamic Bhd v M-IO Builders Sdn Bhd [2017] 2 MLJ 69. The M-IO Builders line of reasoning holds that:
- The validity of an Islamic finance contract must be assessed under the general law governing contracts (principally the Contracts Act 1950), not solely by reference to Shariah principles.
- Section 24 of the Contracts Act 1950 exhaustively lists the grounds on which a contract may be void or unlawful, and non-compliance with Shariah is not among them.
- Neither the Islamic Banking Act 1 983 (now repealed) nor the Islamic Financial Services Act 2013 (IFSA) provides that a breach of a Shariah principle perse invalidates a financing facility.
- If Parliament had intended Shariah non-compliance to void a contract, it would have expressly added such a ground to s 24 of the Contracts Act 1950, but it has not done so.
Observations and Critique
1. The "Shariah-blindness" concern
The judgment reinforces a well-established but highly debated position in Malaysian law: that Islamic finance contracts are, at bottom, governed by civil law, and Shariah compliance is essentially a regulatory and institutional matter (policed by Bank Negara Malaysia's Shariah Advisory Council and institutional Shariah committees) rather than a contractual validity matter. This can be traced back to Bank Kerjasama Rakyat Malaysia Bhd v Emcee Corporation Sdn Bhd [2003] 2 MLJ 408,which the Court expressly endorsed.
From an Islamic finance purist's perspective, this is troubling. It effectively means that a financier can label a facility as "Islamic," charge profit rates exceeding 100% per annum, and the court will enforce the contract so long as it passes muster under the Contracts Act 1950 — even if the pricing mechanism is functionally indistinguishable from usurious interest (riba). The judgment leaves open the question of what remedy, if any, a customer has when an "Islamic" facility is Shariah-non-compliant in substance.
2. The role of IFSA and the Shariah Advisory Council
The Court noted that neither the IBA nor IFSA provides that a Shariah breach invalidates a financing facility. This is technically correct but arguably incomplete. Section 29 of IFSA requires licensed Islamic financial institutions to ensure that their aims and operations, business, affairs, and activities comply with Shariah. Sections56–58 of IFSA establish the role of the Shariah Advisory Council (SAC) of Bank Negara Malaysia as the authority for the ascertainment of Islamic law for the purposes of Islamic financial business, and s 56(1) provides that the ruling of the SAC shall be binding on arbitral tribunals and courts. The judgment does not engage with this regulatory architecture at all, likely because SAPM is nota licensed Islamic bank but rather a scheduled institution under BAFIA (now a prescribed institution under FSA/IFSA). This is a significant gap: the Shariah governance framework under IFSA may not have applied to SAPM directly, but the Court's broader pronouncements on Shariah compliance and contractual validity have implications well beyond this particular factual matrix.
3. The exorbitant profit issue
The Court declined to address the allegation that profit exceeded 100% per annum because it was not pleaded as a Shariah breach and was not within the four questions. This is procedurally sound, but it sidesteps a substantive concern that goes to the heart of Islamic finance: the prohibition of riba (usury/interest). A profit rate exceeding 100% per annum on a facility labelled "Islamic" raises serious questions about whether the arrangement is, in economic substance, a loan at interest rather than a genuine sale-based or agency-based financing. The Court's characterisation of SAPM's business as "Debt Financing" rather than moneylending does not address the Shariah dimension of this concern.
4. Policy implications for whole turnover agreements
The Court's robust endorsement of whole turnover agreements as lawful debt financing instruments is commercially significant. The reasoning that Malaysian businesses should not be deprived of this financing tool, and that prohibiting such agreements would drive financing offshore, is pragmatic and commercially sensible. However, this pragmatism sits uneasily with the Islamic labelling of the facility. If the structure is endorsed purely on civil law grounds, one might question what the "Islamic" label adds — or whether it creates a false assurance of Shariah compliance for customers.
5. The closing reminder
The Court's final observation is telling: "unless it is abundantly clear that a genuine financing agreement or transaction is prohibited by our written law, either expressly or by necessary implication, courts should uphold and enforce the Financing Agreement/Transaction". This is a strong pro-enforcement, pro-commercial certainty statement that aligns with the principle in Lori Malaysia Bhd v Arab-Malaysian Finance Bhd that courts should be slow to strike down commercial transactions. For the Islamic finance industry, the message is clear: the courts will not use Shariah principles as as word to invalidate otherwise lawful contracts.
Summary
This judgment is a significant reaffirmation of the M-IO Builders/Emcee Corporation line of authority. It will be welcomed by financiers and the factoring industry for its commercial certainty and its validation of whole turnover agreements. However, it does leave a gap in the protection available to customers under Islamic finance arrangements, particularly where facilities carry the "Islamic" label but impose pricing that may be inconsistent with the prohibition of riba. The judgment essentially directs Shariah compliance disputes away from the courts and towards the regulatory framework —but without engaging with whether that framework adequately addresses the customer's position. This tension between contractual enforceability under civil law and substantive Shariah compliance remains one of the most live issues in Malaysian Islamic finance jurisprudence.
This article is for general informational purposes only and does not constitute legal advice. Please contact us if you require advice on how these developments may affect your business.
SA Puncak Management v KL Petrogas (Court of Appeal, 25 August 2026) — Key Takeaways
Malaysia’s rise as one of ASEAN’s premier destinations for data centre investment has been remarkable. In just a few years, the country has attracted billions of ringgit in digital infrastructure investment, positioning itself as a critical node in the global digital economy. This momentum reflects strong investor confidence in Malaysia’s connectivity, policy direction, strategic location and expanding digital ecosystem.
Yet success presents a different challenge. The policy question facing Malaysia today is no longer whether it should continue to attract data centre investment; the answer is clearly yes. The more important question is whether these investments are being evaluated through the right lens.
As data centres become the backbone of artificial intelligence, cloud computing, digital financial services and public services, they can no longer be treated as conventional industrial infrastructure. They are strategic national infrastructure, and the way they are evaluated should reflect that reality.
Not All Data Centre Investments Are Equal
It is tempting to view every data centre project as delivering broadly similar benefits, they vary significantly. Some data centres integrate renewable energy into their long-term operating strategy, invest in advanced water management systems, establish regional engineering and research hubs, develop talent and actively strengthen Malaysia’s digital supply chain.
Others may deliver substantial capital investment during construction but generate comparatively limited long-term ecosystem development. Both are investments. But they do not necessarily create the same strategic value for Malaysia.
As competition for energy, water and strategic land intensifies, evaluating projects primarily by investment size risks overlooking what matters most: the quality of their long-term contribution to the country’s digital economy.
A Smarter Tiered Evaluation Framework
This is not an argument for making approvals more complicated or adding unnecessary layers of bureaucracy.
It is an argument for evaluating projects more intelligently. Malaysia should progressively adopt a framework that assesses not only financial investment, but also the national outcomes each project is expected to deliver. Approvals and Incentives should therefore move away from a blanket model but towards a tiered approach that rewards higher-quality commitments.
Because electricity is central to data centre development, grid capacity should be allocated based on credible investor commitments and actual project need. Projects that demonstrate stronger commitments to renewable energy, energy efficiency, local ecosystem participation, talent and long-term operational value should be prioritised, reducing the risk of speculative power requests and unnecessary overbuild. Simply put, the more they invest locally the more power they should get.
Policy and Regulatory Certainty Is an Investment Incentive
One of the greatest advantages Malaysia can offer investors is not simply competitive incentives or available land. It is regulatory certainty.
When evaluation criteria are transparent and strategically aligned, investors can design projects around national priorities from the outset. Expectations become clearer, approvals become more predictable and investment quality improves.
In this sense, regulatory certainty becomes a competitive advantage. It rewards industry players prepared to invest beyond construction by building capabilities, developing talent, strengthening the domestic ecosystem and contributing meaningfully to Malaysia’s long-term digital ambitions.
As the relevant incentive windows and policy frameworks approach their next review cycle, particularly towards 2027, Malaysia should consider whether its incentive architecture is sufficiently calibrated to attract the right type of data centre investments.
A Strategic Opportunity for Malaysia
Malaysia has already demonstrated that it can attract world-class digital infrastructure. The next stage of its journey should be even more ambitious. Rather than aspiring simply to become ASEAN’s largest data centre hub, Malaysia should aspire to become the region’s benchmark for sustainable digital infrastructure governance.
This requires moving beyond success measured by the number of projects approved or the value of investments announced. Success should instead be measured by how effectively each investment strengthens Malaysia’s economy, develops the local ecosystem and promotes responsible resource management. Clear and consistent approval criteria would also promote regulatory certainty in how projects are evaluated, approved and monitored over time.
As the relevant incentive windows and policy frameworks approach their next review cycle, particularly towards 2027, Malaysia should consider whether its incentive architecture is sufficiently calibrated to attract the right type of data centre investments.
The countries that lead the digital economy will not necessarily be those with the most compute power, but those that govern digital infrastructure with the greatest strategic and regulatory foresight.
Malaysia has an opportunity to be one of them. The future of its digital infrastructure should no longer be defined by approving more data centre projects, but by approving the right data centre projects: those with measurable impact, credible sustainability commitments and a clear contribution to the local ecosystem.
This article is for general informational purposes only and does not constitute legal advice. This opinion piece forms part of a series of articles on shaping Malaysia’s digital regulation. As Malaysia deepens its role as a regional data centre and AI hub, the policy debate should move beyond approvals and headline investment value towards a more mature assessment of long-term national benefit, resource resilience and ecosystem development.
Beyond Approvals: Why Malaysia Must Rethink How It Evaluates Data Centre Investments
A case study – the Federal Court’s decision in Acexide Technology Sdn Bhd & Anor v. Chang Heng Keong / Woon Kim Choy [2026] CLJU 2221
What Happened
Acexide Technology Sdn Bhd was founded in 1996 by three shareholder-directors: the majority shareholder and managing director (54% with his son), the technical director (10%) and the project director (36%). All three worked in the business day-to-day.
In 2019, the majority shareholder and managing director used his majority shareholding to remove the two respondents as directors at an EGM. The minutes recorded they were “discharged of all their duties” and the company would stop paying their “salaries” — they would keep only their dividend rights as shareholders.
The two director-employees did not challenge their removal as directors, but filed unfair dismissal claims under section 20 of the Industrial Relations Act 1967 (“IRA 1967”), arguing they were also employees. The Industrial Court and High Court both held they were not “workmen” because, as the “directing mind and will” of the company, they answered to no one. The Court of Appeal reversed. The company appealed to the Federal Court.
What the Court Decided
The Federal Court unanimously dismissed the appeal and held:
"Double hatting" is real. A person can simultaneously be a company director (governed by the Companies Act 2016) and an employee/workman (governed by a contract of service and the IRA 1967). These are distinct legal roles. Removing someone as a director does not automatically end their separate employment.
No need for a single "boss." The argument that co-equal directors answerable to no single person cannot be workmen was rejected. Directors and executive employees are each accountable to the board as a whole — that satisfies the superior-subordinate relationship.
No written contract needed. The IRA 1967 recognises oral and implied contracts. Here, an implied employment relationship was established by: EPF and SOCSO contributions, EA Forms classifying income as salary, inclusion in the register of employees, and financial statements describing payments as "salaries" under staff costs rather than board-approved director's fees.
Removal as director is not dismissal as employee — but stripping "all duties" and stopping "salaries" is. The EGM resolution went beyond removing directorships; it also purported to end the respondents' employment. Since no misconduct was ever proved to justify that dismissal, it was without just cause or excuse. Compensation in lieu of reinstatement was upheld.
The Price Tag: Approximately RM1 Million Per Employee
The Court of Appeal’s award, upheld by the Federal Court, applied Practice Note No. 3 of 2019 of the Industrial Court: compensation in lieu of reinstatement at one month’s salary (plus fixed allowance) for each completed year of service, plus back wages (salary plus allowance) capped at 24 months.
Together, the company was liable for combined awards of more than RM2 million in aggregate. This underscores that getting an executive director’s employment status wrong, and failing to prove just cause or excuse for dismissal, is not a technical or abstract legal point — it is an extremely costly exercise for a corporate employer.
The Federal Court also rejected the employer’s argument that back wages should have been reduced for post-dismissal mitigation earnings or contributory misconduct. The employer never adduced any evidence to support either deduction, and both individuals gave unrebutted evidence that they remained unemployed after their removal. This reinforces that an employer bears the burden of proof on those deductions and cannot rely on generic assertions to reduce what is owed.
Why It Matters to Employers
- Removing a director does not end employment. If a director also has an employment relationship (even an unwritten one), the company must separately follow fair dismissal procedure — show cause, proper grounds, just cause or excuse — or risk an unfair dismissal claim under the IRA 1967.
- "Equal" directors are not immune. Companies cannot assume that senior shareholder-directors fall outside employment law merely because no single person visibly supervises them. Accountability to the board as a whole is enough.
- Your own records will be used against you. How a company treats someone in practice — EPF/SOCSO contributions, EA Form classification, payroll records, and how payments are described in financial statements (as "salary" versus board-approved "director's fees") — is strong evidence of whether an employment relationship exists. Inconsistent documentation is a real risk.
- Structure non-executive roles correctly from the start. If certain directors are genuinely intended to be fee-only with no employment relationship, their remuneration must be structured as properly approved director's fees (not "salary" through payroll), and statutory filings must consistently reflect this.
- If you intend to end both roles, justify the dismissal separately. A company that wants to remove a working director and end their employment must have just cause or excuse for the employment dismissal, independently of the validity of the boardroom removal.
This article is for general informational purposes only and does not constitute legal advice.
Directors Can Also Be Employees: Federal Court Settles the "Double Hatting" Question
A case study - Industrial Court Award No. 950 of 2026
What Happened
The Claimant, a Brunei national, was employed by Schlumberger Global Resources Limited ("SGR Ltd"), a Bermuda company, as international mobile staff. His 2018 employment letter with SGR Ltd contained an express clause (Clause 13) making Bermuda law the governing law and the Bermuda courts the exclusive forum for disputes.
On the same day, SGR Ltd seconded him to work in Kuala Lumpur at Dowell Schlumberger (Malaysia) Sdn Bhd ("the Company"). The secondment letter confirmed that the SGR Ltd employment contract remained valid and unchanged. There was no separate Malaysian employment contract. The Company's role was purely administrative: applying for his employment pass and filing EA tax forms. His salary (in USD) was paid by SGR Ltd throughout.
In 2023, following an alleged assault on a colleague during a pre-assignment visit to Abu Dhabi and a separate internal audit uncovering inflated expense claims, SGR Ltd — not the Company — issued a termination letter dismissing him. The claimant then brought an unfair dismissal claim under section 20(3) of the Industrial Relations Act 1967("IRA 1967") against the Malaysian company.
What the Court Decided
After a trial of the matter, the Industrial Court in June 2026 held it had no jurisdiction to hear the claim, and dismissed it without ever reaching the question of whether the dismissal was with just cause or excuse.
Its reasoning:
One contract, one employer. The secondment letter did not exist independently of the SGR Ltd employment letter and had to be read with it. On secondment, an employee remains employed by the original employer unless that contract ends. Only the original employer (SGR Ltd) could dismiss — and did.
Administrative acts do not make you the employer. The Company's role in applying for the employment pass and filing EA Forms was done purely to satisfy local immigration and tax requirements. These administrative acts did not change who the real employer was.
No extra-territorial jurisdiction. The IRA 1967 is a Malaysian statute with only territorial jurisdiction. Because the true employer, SGR Ltd, was a foreign entity not named as a party, and the claimant had contractually submitted to Bermuda's exclusive jurisdiction, the Court could not hear the claim.
Why It Matters to Employers
- Local admin does not equal local employer. A Malaysian subsidiary that merely handles immigration paperwork and tax filings for a seconded employee will not, by itself, be treated as the employer under the IRA 1967.
- Governing-law clauses work. A foreign governing-law and exclusive-jurisdiction clause in the home-country employment contract can prevent the Industrial Court from hearing a subsequent dismissal dispute, provided the true foreign employer is not joined as a party.
- Get your secondment documentation right. Well-drafted secondment letters that clearly preserve the home-country contract as controlling are an effective way to manage where employment disputes can be brought. All documents — the main contract, the assignment letter, payroll records, and immigration filings — should be internally consistent and should not inadvertently suggest the local entity is the employer.
- Subsidiaries receiving seconded staff should keep their role limited and documented. If the host entity's involvement goes beyond pure administrative facilitation — for example, issuing a local employment contract or paying salary from its own accounts — the outcome could be very different.
This article is for general informational purposes only and does not constitute legal advice.
Does The Industrial Court Have Jurisdiction Over An Employer Outside Malaysia
Earlier this week, the Court of Appeal has answered that question with a clear yes. Provided that the parties have agreed to it.
In this case, Ong Seow Lee, the lender of a friendly loan, sought to recover RM70,000 from Lee Ee Foong, despite having received 50 Litecoins from Lee Ee Foong. The dispute centred on whether the cryptocurrency transfer constituted repayment of the debt, with the lender arguing that Litecoin was not legal tender and therefore could not discharge the loan.
The Court of Appeal unanimously dismissed the appeal and upheld the High Court's decision, holding that the debt had been fully discharged when the lender knowingly accepted the Litecoin as settlement.
Importantly, while the Court stopped short of recognising cryptocurrency as legal tender, it affirmed that digital assets may validly discharge contractual obligations where the parties expressly or impliedly agree to that mode of payment. The key consideration was therefore not the legal status of the asset itself, but the agreement and conduct of the parties.
Two important observations arise:
- The discharge of a debt depends on the agreement and conduct of the parties, rather than the form of the asset used as payment.
- Digital assets, while not recognised as legal tender, may nevertheless constitute valid consideration for contractual purposes.
Although the dispute involved Litecoin, the significance of this decision extends well beyond cryptocurrency. As digital assets continue to evolve from speculative investments into broader commercial and financial applications, courts are increasingly asked to apply established legal principles to new forms of value.
This decision demonstrates that long-established principles of contract law are sufficiently flexible to accommodate digital assets without requiring new legal doctrines or framework.
The takeaway is clear. If parties intend for cryptocurrency or digital assets to settle contractual obligations, that intention should be documented expressly. Key terms such as the type of digital asset, valuation methodology, timing of payment and wallet details should be clearly addressed.
Technology may evolve, but the underlying legal principles remains constant: the courts will generally give effect to what parties have objectively agreed.
This alert is for general information only and is not a substitute for legal advice.